Climate risk in credit: why one score is not enough
How can credit investors assess climate risk when different indicators tell different stories about the same issuer? Relying on a single measure may leave part of the picture unseen.
Drawing on research from the KEDGE-Candriam “Finance Reconsidered” Chair, our paper examines climate risk measurement in US and European corporate bonds. Based on more than 680,000 bond observations from 2004 to 2023, it explores why uncertainty around climate exposure deserves attention alongside the exposure itself.
For institutional investors, the challenge is not simply to choose the “right” indicator, but to understand how robust an assessment is across methodologies. The paper also examines why apparent climate resilience may reflect interest rate sensitivity rather than issuer-specific strengths.
Discover how comparing climate indicators and considering both physical and transition risks can help inform issuer analysis and portfolio construction.
Climate exposure is becoming part of credit analysis, yet there is no universally accepted way to measure it. Indices can differ in scope, data and methodology, leaving investors with conflicting climate betas* for the same bond.
Research from the KEDGE-Candriam ‘Finance Reconsidered’ Chair argues that this dispersion – climate beta uncertainty – is financially material: bonds with greater uncertainty were historically associated with higher subsequent returns, independent of their measured climate exposure.
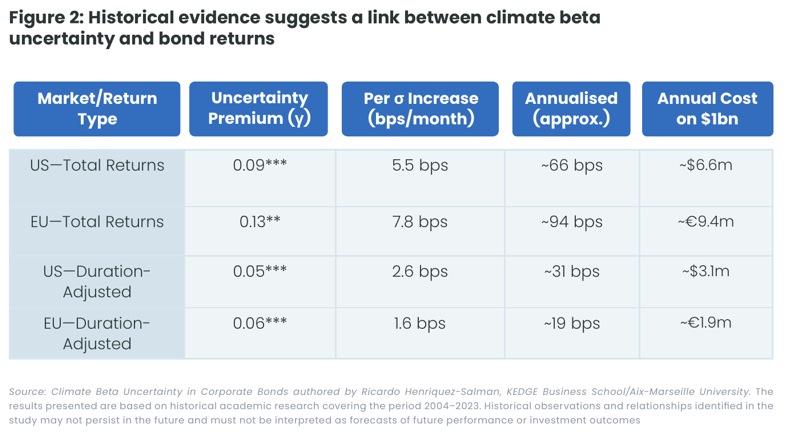
For credit investors, the paper therefore asks a more useful question than ‘Which index is right?’: how robust is an issuer’s climate assessment across methods, and how much uncertainty should be reflected in spreads, selection and portfolio risk?
The implication is clear: Climate-aware credit analysis should compare several signals, test what drives apparent resilience, and distinguish issuer-specific exposure from duration and sovereign effects.
*Climate beta measures how a bond’s returns move with a climate-risk proxy.
Key takeaways
- One climate score is not enough. Comparing datasets and methodologies can reveal uncertainty that a single index may conceal.
- Major climate or regulatory events may improve price discovery by helping markets reassess which issuers are genuinely exposed.
- Duration can look like climate resilience. Investors should separate interest-rate, sovereign and issuer-specific credit effects.
- For portfolio construction, a multidimensional approach can combine physical and transition risks with forward-looking indicators and uncertainty analysis.
For more details, click here